Where’s the Beef?
On AI, the impatience for returns, and the possibility that we're measuring the wrong thing.
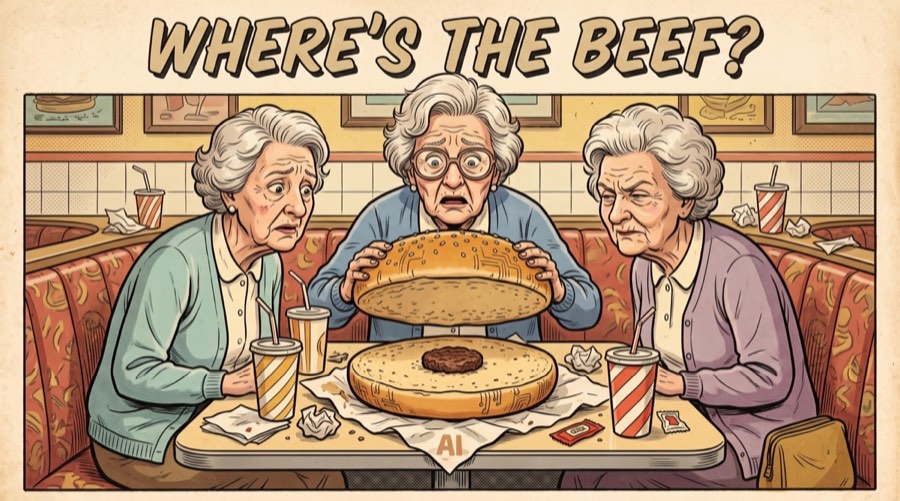
We have seen the enormous bun. Everyone would now like to see the beef.
In January 1984, Wendy’s released a television commercial that would become one of the most memorable advertisements in American history. Three elderly women are standing around an unusually large hamburger. Two of them seem impressed by the size of the bun, until one lifts the top and reveals a ridiculously small piece of meat sitting somewhere in the middle. The third woman, Clara Peller, who was in her eighties at the time, looks at the disappointing offering and asks a question that would eventually find its way into American popular culture: “Where’s the beef?” The commercial was only about thirty seconds long, but the question was so effective that Walter Mondale borrowed it during the 1984 Democratic presidential primaries to challenge Gary Hart’s promises of new ideas. A hamburger advertisement had somehow become a useful way to interrogate political substance. You can watch the original commercial here, and the March 1984 TIME coverage is a fascinating account of how quickly the phrase travelled beyond Wendy’s.
I’ve been thinking about that advertisement lately because it reminds me of the conversation happening around artificial intelligence. There is an enormous amount of money going into AI infrastructure, companies are spending billions on models and applications, and almost every enterprise executive I speak with has some version of an AI strategy. Investors are understandably asking when all this expenditure will produce returns, while businesses deploying the technology are trying to determine whether the benefits justify the costs. The question being asked in boardrooms and investment committees is essentially the same one Clara Peller asked forty-two years ago. We have seen the enormous bun. Everyone would now like to see the beef.
The analogy is amusing, but I think it also exposes a problem with how we’re approaching the economics of AI. Clara Peller was examining a finished hamburger. She could lift the bun and immediately determine whether Wendy’s competitor had delivered what it promised. AI is a technology whose applications, economics and eventual place in society are still being discovered. Some of the revenue being generated today may turn out to be temporary, and some of the companies currently benefiting from the excitement may not survive the decade. But I’m increasingly unconvinced that the revenues and productivity improvements we can measure today will tell us very much about the full economic significance of AI over the next ten or twenty years.
We’ve had this argument before
In 1987, the economist Robert Solow made an observation about computers that became one of the most discussed ideas in the economics of technology. Businesses had been investing heavily in information technology, computers were appearing across offices and industries, and yet the productivity statistics were not showing the transformation that enthusiasts had promised. This became known as the productivity paradox. It was a reasonable criticism because technological progress should eventually improve what an economy can produce with the resources available to it, and economists were struggling to find convincing evidence that computers were doing so.
One of the interesting things about the productivity paradox is what happened afterwards. Computers became cheaper and more capable, software improved, and organisations gradually learned to reorganise work around the technology. In a 2002 paper published by Brookings, Erik Brynjolfsson, Lorin Hitt and Shinkyu Yang examined the relationship between computers and what they called organisational capital. Their argument was that the value of information technology depended partly on complementary investments in skills, processes, management practices and organisational structures. Buying computers was relatively straightforward. Changing a company so that it could make productive use of them was a different undertaking.
This is a useful distinction because it suggests that the economic return from a technology can depend on changes that aren’t immediately visible in the technology itself. A company might spend money installing computers while continuing to organise work in essentially the same way it did before. The computers may improve some individual tasks, but the larger gains can require redesigning the work around the new capabilities. The history of factory electrification offers a related example. Electric motors eventually made it possible to reorganise factories in ways that were difficult under centralised steam-powered systems, but the gains depended on changes to factory layouts and production methods rather than simply replacing one source of mechanical energy with another.
There is a temptation to take these examples and conclude that AI will follow the same trajectory. I’m not sure we can make that assumption. History is full of technologies that looked promising and failed to become economically important, and the fact that computers eventually transformed business doesn’t mean every expensive technology deserves patience. But the examples do establish something worth considering: the time at which a technology becomes technically useful, the time at which companies learn how to deploy it and the time at which its effects become visible across the economy are not necessarily the same.
The internet offers another complication. During the late 1990s, enormous amounts of capital went into telecommunications networks, fibre infrastructure and internet companies on the expectation that demand would continue growing rapidly. The dot-com crash demonstrated that many of the business models and valuations were unsustainable. Yet the underlying expectation that the internet would become a fundamental part of economic life turned out to be correct. Much of the infrastructure survived the companies that financed it, and later businesses built enormous amounts of value on top of capabilities that had been expensive to establish.
This matters for AI because investors and enterprises are asking two questions that are often treated as though they were interchangeable. One is whether today’s AI investments will generate attractive financial returns for the people making them. The other is whether AI will become an important technology around which businesses and societies reorganise themselves. It is entirely possible for the second proposition to be true while a significant number of investments made in pursuit of the first turn out badly.
The problem with measuring what we already know
A few weeks ago, I watched a discussion featuring Jon Gray of Blackstone, where the question of AI investment returns came up in terms that immediately reminded me of Wendy’s advertisement. Blackstone is involved in financing and investing in the infrastructure supporting the AI expansion, so the question is especially relevant to its business. There are data centres to build, enormous amounts of energy to secure, chips to purchase and a growing list of companies hoping that the demand for AI will justify their capital expenditure. At some point, the customers using all this infrastructure have to generate enough economic value to sustain the system.
At the enterprise level, the same question appears in a more familiar form. A company spends money on AI and wants to know whether the deployment has reduced operating costs, increased revenue or improved productivity. These are reasonable things to measure, and there is already credible evidence that AI can improve performance in particular settings. In a study of more than 5,000 customer-support agents, Erik Brynjolfsson, Danielle Li and Lindsey Raymond found that access to a generative AI assistant increased productivity by approximately 14% on average, with substantially larger gains among less experienced workers. The study is useful because it measures what actually happened in a workplace rather than relying on what people said they expected AI to do.
But even when the productivity gains are real, I wonder whether we are measuring enough of what matters. If a developer produces three times as many pull requests with AI, has the company become three times more productive? It depends on whether the additional software solves useful problems, whether the code is reliable and whether anybody wants what has been built. I was struck by a conversation with Claire Vo about how AI is changing software development, particularly the difficulty of finding sufficiently valuable things to build when producing software itself becomes much easier. A team can become dramatically more efficient at producing outputs without producing a corresponding increase in economic value.
The distinction becomes more complicated when AI allows an organisation to do something it previously couldn’t do economically. Consider a financial institution with a million dormant customers. Traditionally, it might send emails, SMS messages or notifications through its mobile application, because those channels are relatively inexpensive and can reach large numbers of people. A human conversation may be more useful for understanding why someone stopped using an account, but employing enough people to call a million customers would be enormously expensive. An AI voice agent changes the range of available options because it can attempt conversations at a scale that would have been difficult to justify with human labour.
I’ve encountered versions of this problem while building BimpeAI, where we work on enterprise AI agents, particularly voice systems. The workflows include re-engaging customers, following up on delinquent loans and handling first-line customer-service requests. These are problems that already have owners inside organisations, existing processes and measurable outcomes. AI becomes interesting because it can introduce conversational interaction into workflows where companies have historically had to choose between relatively cheap automated messages and expensive human intervention.
Suppose an AI agent makes 100,000 calls. We can measure the cost of the calls, the cost of inference, the number of conversations completed and the number of customers who responded. Those metrics tell us something about the deployment, but they don’t necessarily tell us whether it created economic value. If the objective was reactivation, we need to know how many additional customers became active because of the intervention, ideally compared with a group that didn’t receive it. If the objective was collections, we need to understand incremental recovery after accounting for what would have happened anyway. A system can generate impressive operational statistics while producing very little additional value, particularly when the organisation confuses activity with outcomes.
Even those calculations leave something out. If the organisation could never have afforded to make 100,000 human calls, the value of AI isn’t simply the labour cost of calls that would otherwise have happened. Those calls probably wouldn’t have happened at all. The technology has expanded what the organisation can attempt, which means part of the return may come from creating a new operating capability rather than reducing the cost of an existing one. Measuring that requires understanding what changes in customer behaviour, organisational processes and business performance over time.
The return may arrive somewhere else
One reason I’m interested in Voice AI is that it makes the question of how people interact with technology unusually concrete. For most of the history of personal computing, we’ve learned to interact with software through interfaces designed around the limitations of computers. We type commands, click buttons, navigate menus, fill forms and learn the structure of applications before we can get them to do useful things. Even the smartphone, which made computing considerably more accessible, still asks us to understand how the software expects us to behave. A banking application has its own navigation, a shopping application has another, and enterprise software can require substantial training before employees become comfortable using it.
Voice introduces the possibility of changing that relationship. A person should be able to explain what they want to achieve, have the system understand the request, ask for clarification where necessary and take the appropriate action. Achieving this reliably is much harder than generating a convincing voice response. The system needs to understand turns, interruptions, context, the underlying business process and the systems it is authorised to interact with. It must also know when it cannot complete the request and when a human should take over. We spend a considerable amount of time thinking about these problems because a good demonstration of conversational AI is still some distance from a system that can reliably handle unpredictable conversations in production.
If these problems are solved well enough, the implications extend beyond reducing the cost of customer-service calls. Businesses may begin designing products around what customers want to accomplish rather than around the screens they must navigate. Some workflows that currently require specialist training may become accessible through ordinary language. A small business may be able to use capabilities that previously required an entire operations team, while people who struggle with conventional software interfaces may find computers considerably easier to use. There are accessibility benefits here, but also questions about language coverage, reliability, privacy and who gets excluded when a supposedly universal interface doesn’t understand the way they speak.
I don’t think we can put a convincing financial value on all these changes today. We can estimate the cost of a voice conversation and compare it with the cost of a human agent. We can measure successful transactions and operational improvements. What is much harder to calculate is the eventual value of changing how millions of people interact with software, or what kinds of businesses might emerge when interacting with computers requires less specialised knowledge. That uncertainty is part of why I think the long-term return from AI may be much larger, and quite different, from the immediate commercial returns being discussed today.
There is some evidence that the organisational changes are already beginning, even where the financial consequences remain difficult to establish. A 2025 field experiment involving 7,137 knowledge workers across 66 firms found that people who used generative AI tools regularly spent less time on email, but the researchers did not find comparable changes in the overall composition of their tasks. The result is interesting because individuals could change how they performed their own work much faster than organisations could change how work was coordinated. A separate experiment involving 776 professionals at Procter & Gamble found that individuals working with AI could match the performance of teams without AI on certain product-innovation tasks. These findings don’t establish that AI will transform every organisation, but they suggest that the technology is beginning to affect how expertise, collaboration and individual work are organised.
The more consequential changes may therefore require businesses to reconsider their processes rather than simply make existing employees faster at completing existing tasks. That is difficult work because organisations are built around responsibilities, budgets, reporting structures and established ways of making decisions. A technology can become capable of doing something long before a company is institutionally capable of using it. I suspect a considerable amount of the return from AI will eventually depend on whether organisations are willing to change these arrangements, which is a different problem from purchasing more licences or increasing their AI budgets.
The cost of being unprepared
There is an uncomfortable implication to all this, particularly for businesses trying to decide how aggressively they should invest. If the long-term return from AI is uncertain, the financially conservative response is to wait until the technology matures and the economics become clearer. That may be sensible for individual products or expensive infrastructure investments. It becomes more complicated when the technology itself has the potential to change customer expectations, operating models and the basis on which companies compete.
Consider what happens when customers become accustomed to interacting with software conversationally. A business that has spent years improving its mobile application may discover that some customers increasingly expect to accomplish the same tasks without navigating the application at all. A company whose operations depend on large teams manually moving information between systems may find competitors organising similar workflows very differently. A software business that charges according to the number of employees using its product may have to reconsider its economics when customers increasingly expect software to perform work on their behalf. None of these changes requires every company to train a frontier model or build its own data centre, but they do require an understanding of what the technology makes possible and how that might affect the business.
This is where I think the return on AI becomes a longer-term question. A company that experiments today may discover that some of its projects produce very little immediate financial benefit. It may also learn which parts of its operations are suitable for AI, what its customers actually want, what data it needs to organise and which capabilities it should develop internally. That knowledge can become valuable when the technology improves, although it is also possible to spend enormous amounts of money on experimentation without learning anything particularly useful. The distinction matters because almost any unsuccessful technology project can be defended as an investment in future capability.
I don’t think businesses should be given a free pass to spend money on AI simply because the technology might eventually become important. Companies still have employees to pay, customers to serve and shareholders or investors who expect them to allocate capital responsibly. An AI deployment that promises to reduce operating costs should be evaluated against that promise, and a system that creates more problems than it solves shouldn’t be defended indefinitely on the grounds that the future is coming. The immediate economics matter, particularly for startups that cannot afford to wait ten years for a market to develop.
At the same time, evaluating every AI investment exclusively through the next quarter’s cost savings creates another risk. Organisations may prioritise applications with easily measurable returns while neglecting changes that could eventually matter more to their competitiveness. A company might successfully automate a reporting process and save several hundred employee hours, while failing to notice that AI could fundamentally change how its customers expect to interact with the business. The first improvement is easier to put into a spreadsheet. The second may be more important to the company’s future.
I think this is where businesses need to distinguish between investments intended to generate immediate returns and investments intended to develop capabilities for a changing market. Both require discipline, but they cannot always be evaluated using identical expectations. The first should have relatively clear operating metrics and financial objectives. The second needs a credible explanation of what the organisation is learning, how that knowledge might become useful and what would cause it to stop investing. Without that discipline, long-term thinking becomes an excuse for expensive experiments. Without any long-term thinking, a company can become very efficient at operating a business whose customers are gradually moving elsewhere.
Where I think the beef is
I started thinking about Wendy’s advertisement because the question seemed appropriate for the current AI investment cycle. There is so much excitement, expenditure and extraordinary ambition that asking where the returns are feels entirely reasonable. Some of today’s AI revenue may prove to be a short-term phenomenon, supported by experimentation budgets, investor enthusiasm and companies that want to demonstrate to their boards that they are doing something with AI. I wouldn’t be surprised if a number of business models that look attractive today become much less attractive as competition increases, inference becomes cheaper and customers become more demanding about what they’re willing to pay for.
But I also think we’re in danger of confusing the financial performance of today’s AI industry with the eventual economic significance of the technology. The companies generating revenue today are not necessarily the companies that will capture the greatest value tomorrow, and the applications producing the most obvious returns today may not be the ones that ultimately change how businesses operate. The internet created enormous economic value, but much of that value emerged through businesses and behaviours that were difficult to anticipate during its early commercial expansion. The same may happen with AI, although history offers no guarantee that it will.
What makes me interested in the long-term horizon is the possibility that AI changes our relationship with technology itself. We have spent decades learning how to operate computers, designing organisations around software and building businesses around the constraints of existing interfaces. AI creates the possibility of reversing some of that relationship, allowing software to understand more of what we want and perform more of the work required to achieve it. If that becomes reliable and widely accessible, the implications for business, education, healthcare, public services and everyday life could be substantial. There are equally important questions about who controls these systems, who benefits from them, what happens to workers and how much authority we should allow software to exercise on our behalf.
For businesses, I think the danger lies in assuming that the absence of spectacular immediate returns means there is little reason to prepare. Preparation doesn’t have to mean spending recklessly. It can mean understanding the technology, experimenting with problems that matter, developing internal expertise and being willing to reconsider processes that were designed for a different technological environment. The organisations that do this well may be in a better position to adapt as the technology develops. Those that ignore the changes altogether risk discovering that their competitors and customers have moved on while they were waiting for the economics to become obvious.
Perhaps the most valuable return from AI over the next decade won’t be found in the revenue generated by today’s applications or the cost savings reported by today’s enterprise pilots. It may come from the changes those applications make possible in how we work, build businesses and interact with technology. We should continue asking where the beef is, because capital discipline and evidence still matter. But we should also recognise that we’re trying to measure the returns from a technology whose eventual uses and economic consequences are still being discovered. Some of the beef may already be on the table. Much of it may depend on what we learn to build next.
A note on the writing process
This essay was developed through a collaboration between Samuel Adekunle and OpenAI’s ChatGPT.
My writing process begins with long, often unstructured spoken monologues in which I describe my observations, experiences, questions and developing arguments. I use ChatGPT to interrogate those ideas, challenge assumptions, explore historical and contemporary research, and help organise the material into a coherent essay.
The central perspective and conclusions are mine. Research, structure and editorial development are collaborative, and I take responsibility for the final published work.
The precise ChatGPT model designation can be added once verified for publication.
Sources and Inspirations
The following materials informed the essay or provide additional context for readers interested in exploring its arguments. The videos are included as inspirations for the discussion; their specific claims have not all been independently verified.
Advertising, history and the origins of the question
Wendy’s. (1984). Where’s the Beef? Original television advertisement featuring Clara Peller. Watch on YouTube.
TIME. (26 March 1984). Making Hart Stew. Contemporary reporting on Walter Mondale’s use of the Wendy’s slogan during the Democratic presidential primaries. Read article.
Videos that inspired the essay
Jon Gray / Blackstone. Discussion of AI investment, infrastructure expenditure and economic returns. Watch on YouTube. Exact video title and publication date to verify.
Claire Vo. Discussion of AI-assisted software development, productivity and the challenge of identifying valuable work. Watch on YouTube. Exact video title and publication date to verify.
Economic history and the productivity paradox
Solow, Robert M. (1987). We’d Better Watch Out. The New York Times Book Review, 12 July 1987. Discussed in the National Academies’ historical overview of the computer productivity paradox.
David, Paul A. (1990). The Dynamo and the Computer: An Historical Perspective on the Modern Productivity Paradox. American Economic Review, 80(2), 355–361. Read paper.
Brynjolfsson, Erik; Hitt, Lorin M.; and Yang, Shinkyu. (2002). Intangible Assets: Computers and Organizational Capital. Brookings Papers on Economic Activity. Read research.
Empirical research on AI and work
Brynjolfsson, Erik; Li, Danielle; and Raymond, Lindsey R. (2025). Generative AI at Work. Quarterly Journal of Economics, 140(2), 889–942. NBER working-paper version. DOI: 10.3386/w31161.
Dillon, Eleanor W.; Jaffe, Sonia; Immorlica, Nicole; and Stanton, Christopher T. (2025). Shifting Work Patterns with Generative AI. NBER Working Paper 33795. Read research. DOI: 10.3386/w33795.
Dell’Acqua, Fabrizio, et al. (2025). The Cybernetic Teammate: A Field Experiment on Generative AI Reshaping Teamwork and Expertise. NBER Working Paper 33641. Read research. DOI: 10.3386/w33641.
Bick, Alexander; Blandin, Adam; and Deming, David J. (2024, revised 2025). The Rapid Adoption of Generative AI. NBER Working Paper 32966. Read research. DOI: 10.3386/w32966.
Humlum, Anders; and Vestergaard, Emilie. (2025, revised 2026). Still Waters, Rapid Currents: Early Labor Market Transformation under Generative AI. NBER Working Paper 33777. Read research. DOI: 10.3386/w33777.